Utah Based Mortgage Broker. Licensed in UT, FL, ID, PA, TX
See if you qualify before you fall in love with a house.
Answer a few questions about your income, debts, and credit estimate. In about 2 minutes you will see realistic loan options, explained in plain English, the way an underwriter would look at it. No pressure. No sales call required.
LenditHome Powered By Alpha Home Lending, Inc.
Serving Utah, Florida, Idaho, Pennsylvania, and Texas.
Start here. It takes about 2 minutes.
Step 1 of the checker. Your full result opens in the tool.
Next, the checker runs your income and debts like an underwriter and shows your options side by side.
Where are you starting?
Pick your path. Each one opens the checker with your situation in mind.
I am buying my first home
See how much house your numbers support, what your down payment could be, and how much cash you will need at closing.
Start the checker →I am buying my next home
Run your real numbers before you list, tour, or write an offer, so there are no surprises after you fall for a place.
Start the checker →I want to refinance
See whether a new loan actually lowers your total cost. Not just your rate. If it does not save you money, we will say so.
Start the checker →Two minutes. Three steps. A straight answer.
Most calculators guess at a payment. This one runs your numbers the way an underwriter would.
Tell us the basics
Your income, your monthly debts, a credit estimate, and what you want to buy. About 2 minutes, right on your phone.
We run it like an underwriter
The checker weighs your debts against your income and matches you to real loan programs and their guidelines.
See your options side by side
Monthly payment, cash you will need, and what each option costs, in plain English. Then you decide what happens next.
What you will not get. No obligation. No pressure call. No result held back until you hand over your phone number. The result is yours either way.
Why these answers are realistic.
A payment estimate is easy. A qualification answer takes more work. Here is the difference.
Built on underwriting logic
The checker weighs your debts against your income, the same starting point a real underwriter uses. It is not a payment multiplier.
Your estimate, your control
It runs on the credit range you enter, and it shows you what would change the answer, so you can test scenarios before you commit to anything.
A human stands behind it
The tool starts the work. A real loan officer reviews your result and can verify it with you, line by line, whenever you are ready.
| Home price | $425,000 |
| Down payment | $42,500 (10%) |
| Estimated loan amount | $382,500 |
| Programs compared | Conventional, FHA, VA |
This sample uses round numbers to show the format. Your checker result uses your real numbers and adds an estimated monthly payment and cash needed for each option it finds.
No surprise fees. Here is what a loan actually costs.
Most buyers get surprised by at least one fee. We would rather explain every one of them up front.
Rate versus APR
Your rate is what the loan charges in interest. APR rolls in most lender fees, so it is the better number for comparing two offers.
Lender fees
Charges from whoever makes your loan. They vary by lender, and you will see every one of them, line by line, on a Loan Estimate before you commit.
Third party costs
Appraisal, title work, and similar services from outside companies. Nobody pockets these. They are the cost of verifying the home and the loan.
Prepaids and escrow
These are not fees. They are your own property taxes and homeowners insurance, paid early and held in your escrow account.
Typical closing costs
Across the industry, closing costs usually run about 2 to 5 percent of the home price. That is a range, not a quote. Your Loan Estimate gives you the real figures.
How we get paid
As a broker, our pay comes from the lender, from you, or a mix of both, depending on the loan you choose. Either way it is disclosed in writing on your Loan Estimate.
Get quotes from other lenders too. Research from Freddie Mac shows one extra quote saves borrowers about $1,500 on average. We will happily show you how to compare Loan Estimates line by line.
Your rate is personal. Here is what actually sets it.
Any site can flash a low rate. That number means nothing until it is run against your numbers. Three things move it most.
Your credit profile
Stronger credit usually means a lower rate and more program options. The checker starts from the range you estimate, so you can see where you stand today.
Your down payment
More money down usually means a smaller loan and better pricing. Less down can still work. The right answer depends on your whole picture, not one rule.
Your loan type
Conventional, FHA, VA, and USDA loans price differently and follow different guidelines. Comparing them side by side is the whole point of the checker.
Loan options, in plain English.
Every program answers one question. Is this one built for someone like me?
Conventional
For buyers with solid credit who want flexible terms. Down payment from 3% for qualified first time buyers. Good to know: put less than 20% down and mortgage insurance usually applies until you build equity.
Check this option →FHA
For buyers rebuilding credit or keeping cash in hand. Down payment from 3.5%. Good to know: FHA charges mortgage insurance, and part of it usually stays for the life of the loan.
Check this option →VA
For veterans, service members, and eligible spouses. Often no down payment at all. Good to know: a VA funding fee applies to most loans, and you need your eligibility certificate.
Check this option →USDA
For buyers in eligible rural and suburban areas. Often no down payment. Good to know: income limits and area maps decide eligibility, so the checker asks where you are buying.
Check this option →Jumbo
For homes priced above standard loan limits. Down payment from 10%. Good to know: jumbo loans usually ask for stronger credit and cash reserves, so documentation matters more.
Check this option →Refinance and Cash Out
For owners who want a better loan, a lower cost, or cash from equity. Good to know: a lower rate alone is not a win. Total cost over time is the number that matters.
Check this option →From checking to closing.
Four steps, and you can stop after any one of them. The checker result is yours either way.
Check
Run the checker and see where you stand. About 2 minutes, today, from your phone.
Talk it through
A short call with Austin to walk your options. Only if you want one. Plenty of buyers just take the result and think.
Get preapproved
We verify your income, debts, and documents so sellers take your offer seriously. This is the step that wins houses.
Offer to closing
Appraisal, final underwriting, and signing. You get updates at each stage, and every fee explained before you sign, not after.
 LOAN OFFICER
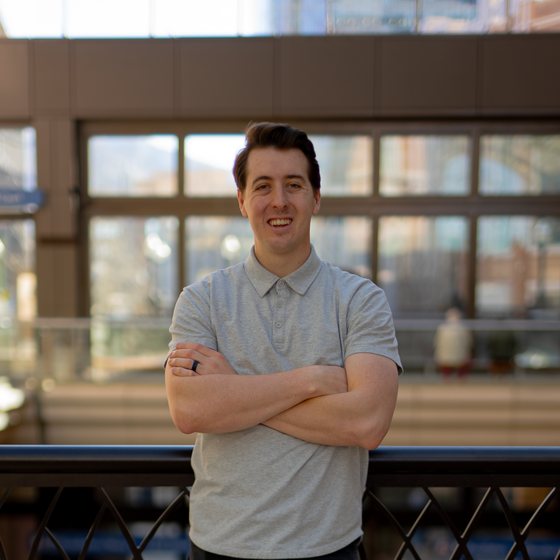
Meet Austin Pugmire
Your mortgage guide at LenditHome. Pleasant Grove, Utah.
Austin bought his first home at 23, and that experience is what pulled him into this business. He brings six years of sales experience and a background in real estate media, which is a useful mix. He knows the numbers, and he knows how to explain them so they actually make sense.
His whole approach is transparency, education, and a personal touch. When he is not working a loan, he is outdoors with his wife and baby girl. Whether this is your first home or your fifth, he will make the financing simple, clear, and tailored to you.
(208) 821-0687 · [email protected] · 978 S Main St, Pleasant Grove, UT 84062 · NMLS ID 2652359
“I use Austin for all my loans as a real estate investor and as a realtor I recommend him to all my clients. He’s fast. He’s good and he’s never let me down. I highly recommend Austin and his team. He’s done over a dozen loans for me in the last year.”
“Austin is the person to go to when it comes to mortgages. He works hard to find the best deal and clearly explains every detail as a loan officer. He is incredibly patient and very client-friendly. We will definitely work with Austin again for our next purchase.”
“Austin went above and beyond for us and made the whole process so easy! He’s so knowledgeable and kept us in the loop constantly. Highly recommend!”
“Austin was amazing to work with he was always open to communication he helped us with every step I 100% recommend going through them and working with them”
“Austin was extremely responsive and knowledgeable throughout the entire process. He provided all necessary information promptly and helped my clients close quickly and efficiently. He was smooth, organized, and very easy to work with. Highly recommend!”
“Austin is one of the most reliable and attentive professionals I’ve worked with. He approaches everything with genuine care for the people he’s helping.”
Six of our 18 Google reviews, shown word for word. Read all 18 on Google.
Buying your first home in UT, FL, ID, PA, or TX?
You do not need everything figured out before you start. You need your numbers. The checker shows a first time buyer three things: how much house your income supports, what your down payment options look like, and how much cash you will need at closing.
Many of our buyers use state down payment help. The checker asks about it, and we flag what you may qualify for.
Straight answers.
The questions that stop most people from clicking, answered the way we would answer them on the phone.
Will checking hurt my credit?
No. The checker runs on the credit score range you estimate. It does not pull your credit. If you later choose to move forward with a full application, a lender pulls your credit only with your permission, and we will tell you before it happens.
Do I have to talk to a salesperson?
No. Your result is yours the moment the checker finishes. If you want a human to walk through it with you, Austin is a call or a text away. If you do not, that is fine too.
How long does the checker take, and what happens after?
About 2 minutes. Afterward you see your loan options side by side, with estimated payments and the cash you would need. What happens next is entirely your call.
How long does closing take?
Most closings take about 30 days, and the seller's needs usually set the exact date. If you need to move faster, we can close in as little as two weeks when the loan allows it. If you need longer, we will work around your timeline instead. Tell us the date you need and we will build the plan around it.
How are you paid?
We are a mortgage broker. Our pay comes from the lender, from you, or a mix of both, depending on the loan you choose. It is always disclosed in writing on your Loan Estimate before you commit to anything.
What if I do not qualify yet?
You still get a straight answer, and you get the clearest next step with it. What to pay down, what to save, or what to wait on, based on your actual numbers. Most people who do not qualify today are closer than they think.
How much do I need for a down payment?
It depends on the program. VA and USDA loans often need nothing down for eligible buyers. FHA starts at 3.5%. Conventional can start at 3% for qualified first time buyers. 5% is common for other buyers. The checker sorts out which ones fit you.
Can you lend in my state?
We serve Utah, Florida, Idaho, Pennsylvania, and Texas. If you are buying in one of those five, we can help. If you are not, ask anyway and we will point you to someone local we trust.
Why use a broker instead of my bank?
A bank sells its own menu. A broker shops your loan across multiple lenders and brings you the comparison. Same application work for you, more options behind it, and one person who answers to you instead of to a sales quota.
Home loans should make sense.
Start by seeing where you stand.
About 2 minutes. No pressure. A real person in Utah reviews your result.
Check If You QualifyPrefer to talk? Call Austin at (208) 821-0687.